
For most Austin homeowners, the fastest practical routes to fund a pool are unsecured personal pool loans, a HELOC or home equity loan, a cash-out refinance, or financing arranged directly through your builder. If your equity is thin or you want to avoid putting a lien on your house, unsecured pool loans from lenders like HFS Financial(https://www.hfsfinancial.net/location/texas/pool-loans-austin-texas/) run from about $5,000 to $450,000 with terms up to 30 years. If you’re sitting on solid home equity and rates are favorable, HELOCs and cash-out refinances often beat unsecured rates, but they take longer to close and put your house on the line.
Here’s what those numbers mean in practice:
- Unsecured pool loans: roughly $5,000 to $450,000, terms of 1 to 30 years, no home equity required, funding often in 24 to 48 hours after approval.
- Equity-based options (HELOC, home equity loan, cash-out refi): limited by your available equity, terms often 10 to 30 years, but funding typically takes several weeks due to appraisal and closing requirements.
Pro Tip: Before you call a single contractor, get soft-pull prequalification from two or three lenders. It costs you nothing, doesn’t touch your credit score, and gives you a real number to compare against contractor-arranged financing.
Key Takeaways
The right pool financing route in Austin depends on your equity, credit profile, and timeline, not a single “best” product for every homeowner.
| Point | Details |
|---|---|
| No equity? Go unsecured | Loans from HFS Financial or Lyon Financial run $5,000 to $450,000 with terms up to 30 years and no lien on your house. |
| Strong equity favors HELOC or cash-out refi | Equity-based options often beat unsecured APRs but take 2 to 6 weeks to close due to appraisal requirements. |
| Prequalify before you shop contractors | Soft-pull prequalification takes minutes and doesn’t affect your credit score. |
| Permits shape your timeline | Austin requires site plans, engineering drawings, and 48-inch fence barriers before construction starts. |
| Longhorn Pools coordinates both sides | Longhorn Pools connects design, build, and financing so disbursements match construction milestones for Austin projects. |
Where to verify permits, licensing, and lender details
- City of Austin Development Services for site plan and permit requirements specific to residential pools.
- HFS Financial’s Austin loan page and Lyon Financial’s Texas pool loan page for current rates and prequalification.
- BBB profiles for any lender or contractor you’re vetting, to check ratings and complaint history before committing.
This article provides general information about pool financing and is not financial advice. Confirm current rates, terms, and eligibility directly with lenders before making a decision.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Table of Contents
- Pool Financing Options in Austin at a Glance
- How Does Each Financing Option Actually Work?
- What Local Permits and Rules Affect Your Financing Choice?
- Which Lenders and Partners Actually Serve Austin?
- How Do You Choose the Right Financing Route?
- What’s the Typical Timeline From Application to Finished Pool?
- Longhorn Pools: A Local Path for Design, Build, and Financing
- Get a Local Quote and Financing Guidance From Longhorn Pools
- Sources
Pool Financing Options in Austin at a Glance
The table below lines up the main routes Austin homeowners use to fund a pool project, based on typical market terms reported by lenders serving Texas.
| Loan Type | Typical Max Amount | Typical APR Range | Typical Term | Requires Home Equity? | Funding Speed | Best For |
|---|---|---|---|---|---|---|
| Unsecured personal pool loan | $5,000 to $450,000 | Fixed rates | 1 to 30 years | No | 24 to 48 hours after approval | Homeowners with limited equity who want speed |
| HELOC | Based on available equity | Variable, often below unsecured rates | 10 to 30 years (draw + repayment) | Yes | 2 to 6 weeks | Homeowners with strong equity and a phased project |
| Home equity loan | Based on available equity | Fixed, competitive with HELOCs | 5 to 30 years | Yes | 2 to 6 weeks | Homeowners who want a fixed payment against equity |
| Cash-out refinance | Based on equity and new loan limits | Tied to current mortgage rate environment | 10 to 30 years | Yes | several weeks | Homeowners who can improve or match their current mortgage rate |
| Contractor/dealer financing | Varies by dealer program | Varies, sometimes promotional | Varies, often 10 to 30 years | Usually no | Varies by builder and lender partner | Homeowners who want financing bundled with the build contract |
| Credit card / short-term line | Card limit or line amount | High compared to installment loans | Revolving | No | Immediate | Small renovations or gap funding only |
A few things the table can’t fully capture: unsecured pool loans skip the appraisal step entirely, which is the single biggest reason they fund faster than anything tied to your house. HELOCs and home equity loans put a lien on your property, so missed payments carry real consequences beyond your credit score. Cash-out refinancing resets your entire mortgage, which means closing costs on the whole loan amount, not just the cash you’re pulling out. Contractor financing varies wildly by dealer, so read the fine print on deferred-interest promotions before you sign anything.
How Does Each Financing Option Actually Work?
Unsecured personal and pool-specific loans
“No home equity required” means exactly what it says: the lender isn’t putting a lien on your house, and there’s no appraisal holding up your timeline. HFS Financial’s Austin lending program offers loans from $5,000 to $450,000 with fixed rates and terms up to 30 years, and you can prequalify with a soft credit pull that doesn’t dent your score. Lyon Financial runs a similar Texas-focused program, capping loans at $250,000 with terms up to 30 years and offering specialized support for certain borrower groups, including veterans.
Your rate on these loans depends almost entirely on your credit profile and the term you choose. LightStream, Truist’s online lending arm, reserves its lowest advertised rates for borrowers with excellent credit who enroll in AutoPay, and its unsecured pool loans typically top out around $100,000, smaller than HFS or Lyon’s ceilings but with no fees or prepayment penalties. A soft pull, by the way, is just a preliminary credit check that shows you likely rates without triggering a hard inquiry. The hard pull only happens once you commit to a full application.
HELOC and home equity loans
These use your house as collateral, which is the tradeoff for often-lower rates. A HELOC works like a credit line against your equity, with a draw period followed by repayment. A home equity loan gives you a lump sum with a fixed payment from day one. Both usually require an appraisal, which adds weeks to your timeline and a real cost if the deal falls through. If you’re financing a $100,000 pool and plan to stay in your house for a decade or more, the lower APR can save real money over the life of the loan. If you’re not sure how long you’ll own the house, a lien tied to a discretionary purchase like a pool is worth thinking through carefully.
Cash-out refinance
This makes the most sense when refinancing also improves or matches your existing mortgage terms. You’re not just borrowing for the pool. You’re resetting your whole mortgage, so closing costs apply to the full new loan balance, not just the cash you’re taking out. If your current mortgage rate is well below where new loans are pricing, a cash-out refi usually costs you more in the long run than it saves.
Contractor and dealer financing
Builder-arranged financing, sometimes called dealer financing, can offer staged disbursements tied to project milestones rather than one lump payment. That can work well for a multi-phase build. It also means terms and disclosures vary dramatically from one contractor to the next, so ask directly whether the loan funds you or pays the contractor, and whether any promotional rate is deferred interest (where missing the payoff window triggers retroactive interest on the full balance).
Short-term options for small jobs
Credit cards or personal lines of credit can cover a small resurfacing job or equipment upgrade, but the APRs are usually much higher than installment loans built for pool projects. Use these for gaps, not for funding a full build.
What Local Permits and Rules Affect Your Financing Choice?
Austin has its own permitting rules that shape both your budget and your timeline, and lenders pay attention to both. The city requires site plans and engineering drawings for residential inground pools, plus compliance with safety barrier codes, including a minimum 48-inch fence height with self-closing, self-latching gates. Budget for permit fees and the possibility of plan revisions if your first submission doesn’t clear review. Longhorn Pools has put together a more detailed homeowner guide to Austin pool building regulations if you want to walk through the specifics before you talk to a lender.
Contractor licensing matters too, and not just for quality control. Lenders that disburse funds directly to your contractor generally prefer working with licensed, verifiable builders. You can check a contractor’s standing through the Texas Department of Licensing and Regulation, which lists licensing status and any complaint history.
Austin’s building season runs hot and heavy through spring and summer, which affects contractor availability and can push payment schedules if you’re financing in staged draws. A few practical budget items to keep in mind:
- Permit and plan-review fees, which vary by project scope and can require revisions.
- Engineering drawings, often required for pools over a certain size or on sloped Hill Country lots.
- HOA approval, if applicable, which can add weeks before construction even starts.
- Barrier and fencing costs to meet the 48-inch code minimum.
Typical inground pool costs in Austin run into a wide range depending on size, materials, and site conditions, particularly on the region’s rockier Hill Country terrain. Get local quotes early since soil conditions alone can shift your budget meaningfully from one lot to the next.
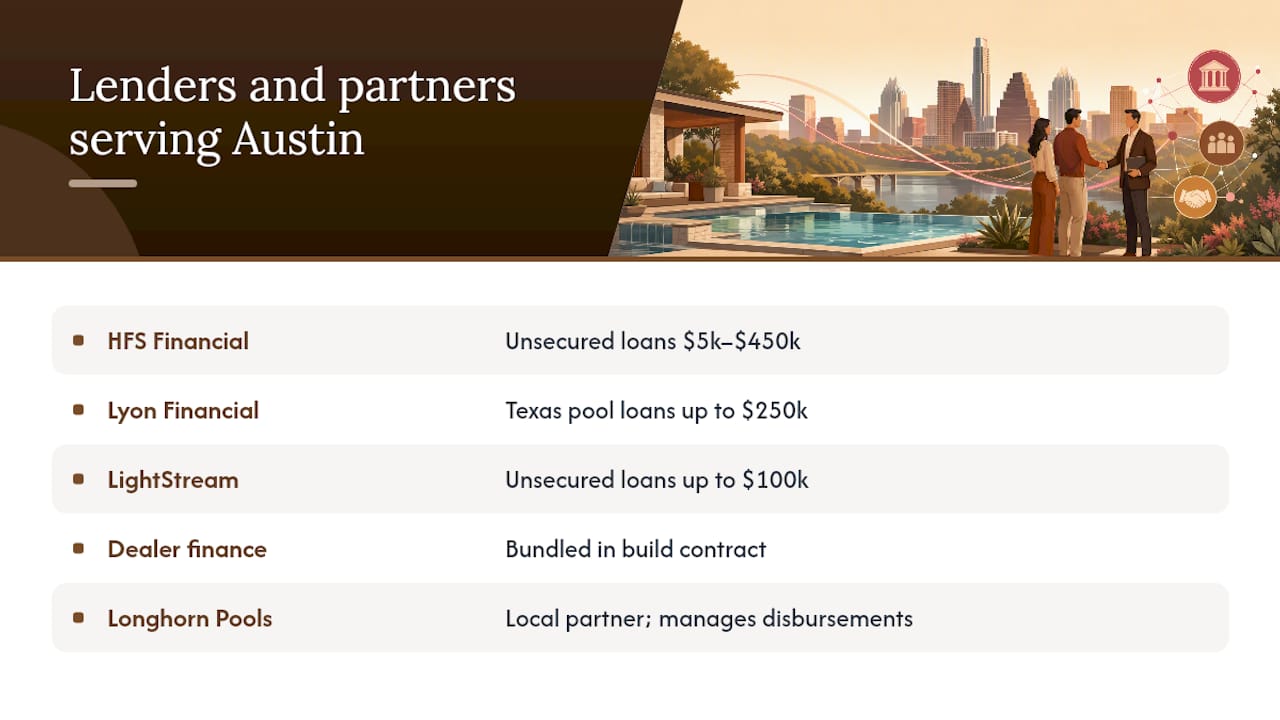
Which Lenders and Partners Actually Serve Austin?
A handful of names show up consistently when Austin homeowners start shopping pool financing. Here’s what each brings to the table.
HFS Financial offers unsecured pool loans from $5,000 to $450,000 with fixed rates, terms up to 30 years, and soft-pull prequalification that takes about a minute. No home equity required, which makes it a common first stop for homeowners who don’t want a lien on their house.
Lyon Financial runs a Texas-specific pool loan program capped at $250,000 with terms up to 30 years, including specialized programs for certain borrower groups such as veterans. Its BBB profile is worth a look before you apply, same as any lender you’re vetting.
LightStream targets borrowers with excellent credit who want a fast, unsecured loan with no fees and no prepayment penalties, plus a rate discount for enrolling in AutoPay. Loan amounts run smaller than HFS or Lyon, generally up to $100,000.
AquaPools and other local dealer finance programs offer financing bundled directly into your build contract, sometimes with staged disbursements tied to project milestones. Terms vary by dealer, so read every disclosure closely.
Viking Capital is another name that shows up in the pool-lending space, offering financing programs aimed at pool purchases; as with any lender, confirm current rates and terms directly since they shift.
Longhorn Pools works as an on-the-ground local partner rather than a lender itself, coordinating with financing options and handling build disbursement scheduling for Austin-area projects. If you want a single point of contact managing both the design and the money side, Longhorn Pools’ financing page is a good place to start that conversation.
Before committing to any lender, check a few trust signals: BBB rating, published fee disclosures, whether there’s a prepayment penalty, and whether funds go to you or directly to your contractor. Those details matter more than the headline rate.
Pro Tip: Get prequalified with two or three lenders and collect two or three contractor bids before you sign anything. Having real numbers on both sides gives you actual negotiating leverage instead of just a gut feeling.
How Do You Choose the Right Financing Route?
Start with five questions: What’s your credit score? How much home equity do you actually have? What’s your timeline? How big is the project? And are you comfortable putting a lien on your house for a backyard upgrade?
When you call lenders, ask these directly:
- What’s the APR with and without AutoPay or autopay-equivalent discounts?
- Are there origination fees, and how are they calculated?
- Is there a prepayment penalty if I pay the loan off early?
- How fast does funding actually happen once I’m approved?
- What documentation do you need, and is an appraisal required?
- Do you fund me directly, or do you pay my contractor?
Watch for red flags: undisclosed fees that surface late in the process, a lender that insists you use only their approved contractor list, unusually long fund-hold periods after approval, or any pressure to sign before you’ve had time to compare offers.
A couple of quick scenarios show how this plays out. Excellent credit, limited home equity: an unsecured pool loan through HFS or Lyon usually makes the most sense. Strong equity and a mortgage rate you’re happy with: a HELOC or home equity loan probably beats refinancing. Strong equity but a mortgage rate well above today’s market: a cash-out refinance might be worth running the numbers on.
What’s the Typical Timeline From Application to Finished Pool?
Timelines vary a lot by financing type, and it’s worth mapping them against your construction schedule before you pick a lender.
- Prequalification (same day): Soft-pull prequalification with an unsecured lender usually takes minutes online.
- Full application and approval (1 to 5 business days for unsecured loans; 2 to 6 weeks for HELOC, home equity, or cash-out refinance): Equity-based products need an appraisal and closing, which is where most of the extra time goes.
- Funding (24 to 48 hours for unsecured loans once approved; additional closing time for equity products): This is when money actually becomes available for disbursement.
- Design and permitting (several weeks): Site plans, engineering drawings, and city review happen in parallel with or right after financing.
- Excavation, structure, and finish work (weeks to a few months depending on scope): Disbursement cadence from your lender should line up with build milestones.
- Equipment commissioning and final walkthrough: The last draw typically releases once the pool passes inspection and startup is complete.
Pro Tip: Line up your financing before you finalize contractor bids, not after. A prequalified budget gives you real negotiating room, and it keeps a contractor from padding a quote once they sense you’re financing on the fly.
Longhorn Pools: A Local Path for Design, Build, and Financing
Longhorn Pools designs and builds custom inground pools, plunge pools, and commercial pools across Austin and the Texas Hill Country, and also handles renovations for homeowners upgrading an existing pool rather than starting from scratch. What sets the local approach apart is coordination: instead of juggling a lender, a contractor, and a permitting timeline separately, Longhorn Pools works through all three as one connected process.
The typical path looks like this:
- Initial consultation: Discuss project scope, site conditions, and rough budget range.
- Bids and scope refinement: Finalize design details and get a firm project estimate.
- Financing guidance: Longhorn Pools helps homeowners understand which routes, from unsecured pool loans to equity-based options, fit their situation, and connects them with financing resources.
- Disbursement coordination: As construction hits milestones, Longhorn Pools manages the schedule so draws align with actual progress on site.
If you’re renovating rather than building new, the pool renovation process follows a similar financing logic, just with a smaller scope and often a shorter timeline. Homeowners who want to see the local service area directly can check the Austin location page for coverage details.
Why local partnerships matter for Austin pool projects
Permit friction is where a lot of pool projects lose weeks, and it’s almost always avoidable. A builder who’s filed dozens of applications with the City of Austin knows which site-plan details trigger a revision request before you ever submit, and that knowledge alone can save you a month.
There’s also a quieter benefit that doesn’t show up in loan comparison charts: when your contractor and your financing are coordinated instead of running on separate tracks, staged disbursements stop being a source of anxiety. You’re not calling a lender asking why a draw hasn’t released while your crew sits idle. Central Texas soil conditions, Hill Country grading, and the region’s tight summer construction season all reward a builder who’s navigated them before. Pair that local knowledge with a financing plan you’ve already vetted, and you eliminate most of the surprises that turn a straightforward pool build into a stressful one.
Get a Local Quote and Financing Guidance From Longhorn Pools
Longhorn Pools gives Austin homeowners something the national lenders on this list can’t: someone local managing the build and the money side together, so your financing draws actually match your construction progress instead of running on a separate clock.

Whether you’re planning a full custom build or exploring options for the Signature Series, the smart move is to get prequalified with a lender or two while you request your Longhorn Pools estimate. That way you walk into your design consultation already knowing your budget range, and Longhorn Pools can help map the right financing route to your specific project scope. Reach out through the financing page to start that conversation and get a local quote moving.
Sources
- Financing a Pool in Austin, TX: No Equity Required | HFS Financial
- Swimming Pool Financing | LightStream by Truist
- Texas Pool Loans | Apply Today
- Tdlr